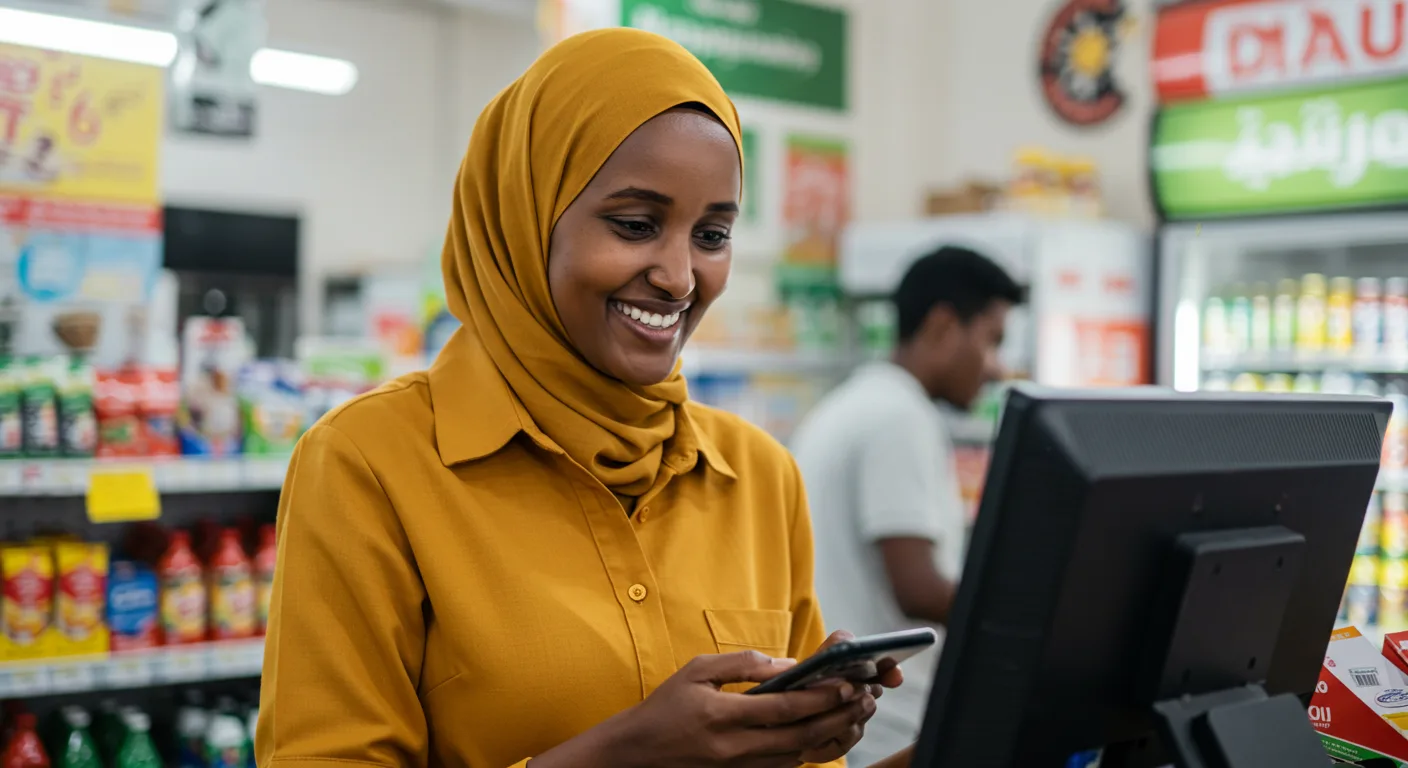
A familiar counter. A connection to the world.
A customer walks into your shop to buy groceries, then asks for help sending money to family abroad. As an approved sending agent, your business can help that customer start a money transfer through WODI. You assist with the required recipient information, available delivery options, and the cost shown before confirmation.
A sending agent works at the start of the transfer. A paying agent works at the receiving end, helping the recipient collect their money. For cash pickup, that means paying out the transfer at an approved local location after the required checks.
Our network spans more than 200,000 paying agents across 120 countries. That reach connects local service with international destinations. The services available to any individual store depend on its approval, location, and participating partner coverage.
Sending agent
Helps a customer initiate a transfer to a supported destination, which may include a bank account, mobile wallet, eligible card, or cash-pickup location.
Paying agent
Delivers an incoming transfer to its recipient. At a cash-pickup location, the recipient follows their payout instructions to collect cash.
A store can apply to offer both
Sending and paying are distinct services. Your agent agreement and WODI dashboard identify the services your location is approved to provide.
Your store becomes a financial access hub—not a bank.
A financial access hub is a familiar place where people can get help using approved financial services. Your shop continues to be an independent business. Becoming a WODI agent does not turn it into a bank, a bank branch, or a licensed financial institution, and does not authorize it to offer services outside its agreement.
WODI is a financial technology company. Regulated financial services are provided through the applicable regulated partners. Your role is to facilitate the services approved for your location, follow the required procedures, and help customers understand their options.
For customers, the value is practical: a nearby counter, a person who can explain the process, and access to supported ways to send or receive money—including cash pickup for people without a bank account.
Why become a sending agent?
An agent service can give customers another reason to visit your business and another reason to return. It builds on something a local store already has: relationships with the people around it.
Add a source of revenue
Earn commissions on eligible transactions under your approved agreement. Earnings depend on activity, service mix, and applicable rates; no income level is guaranteed.
Create more opportunities for repeat visits
People who come in for a transfer may also shop for everyday essentials. Helpful service can strengthen customer relationships, although additional foot traffic and sales are not guaranteed.
Make your store more useful
Customers can combine a familiar shopping visit with assistance sending money or collecting an approved cash payout. Additional services depend on separate eligibility and approval.
Support people in your community
Help customers navigate a transfer and connect with loved ones. Paying-agent services can also give recipients a local way to access cash.
Work with tools and onboarding support
Use the WODI tools available to your location to review approved activity and receive guidance on your services, operating process, and commission schedule.
What this can mean for a neighborhood business
Our neighborhood-shop case study describes Aly, a Bronx business owner who wanted to make financial services more accessible to his community. It illustrates the opportunity to attract repeat visitors, earn transaction commissions, and help people access services at a familiar counter.
That story is an example of the opportunity, not a forecast for another store. Each business has its own customer demand, costs, service availability, and approval requirements. The goal is to build a useful service that fits your business and can be operated responsibly.
What should you prepare before applying?
WODI uses a rigorous selection and onboarding process. Not every store qualifies, and a completed application does not automatically activate agent services. Know Your Business (KYB) review helps establish who owns and controls the business, what it does, and how it intends to use the services.
The following preparation checklist draws on the Level 3 business onboarding form. The onboarding team will confirm the current documents required for your legal structure, country, partner program, and requested services. Equivalent local documents may be appropriate.
Business identity and registration
Prepare the legal name, any trading name, entity type, formation date and jurisdiction, registration number, and business contact details. Provide a U.S. EIN or the relevant foreign tax ID and issuing country, as applicable.
Formation and governing documents
Prepare the applicable registration or incorporation documents, operating agreement or bylaws, certificate of good standing, and tax-registration evidence. The appropriate documents differ for a company, partnership, sole proprietor, or other entity.
Business address
Provide the operating address and any different registered or mailing address. The Level 3 checklist calls for address evidence issued within 90 days, such as a utility bill, bank statement, lease, or another accepted document.
Ownership, management, and signing authority
Prepare an ownership chart showing intermediate entities and ultimate individual owners. The Level 3 checklist requests information on direct or indirect owners with 10% or more ownership, as well as relevant controlling persons, managers, directors, signatories, and the applicant’s authority. The onboarding team confirms the requirements for your program.
Identity information for the relevant people
Expect requests for names, dates of birth, residential addresses, tax identifiers where applicable, and unexpired government-issued photo identification for the people covered by the review.
Business activity and intended use
Describe your products, services, locations, staff, customers, suppliers, and primary markets. Explain which agent services you want to offer and how they fit your business.
Financial information and source of funds
Prepare a recent business bank statement and current financial statements. The Level 3 form allows newly formed businesses to provide projections instead of historical financial statements. It also requests information on revenue, profit, cash activity, available cash, debts, assets, and the source of assets. Five years of historical statements are listed as optional in that form.
How the selection and activation process works
Document collection is the start of review, not the approval decision. We need to understand the business, the people responsible for it, the intended activity, and whether the requested services fit the applicable program.
Tell us about your business
Start the WODI business and agent application. Identify your location and your interest in sending services, cash payouts, or both.
Submit the requested information
Provide complete, consistent business, ownership, identity, and financial information through the secure onboarding process. Sensitive identity documents belong in that process, not in a public comment or an ordinary email.
Complete eligibility and compliance review
WODI and the relevant partners review the application and supporting information under the applicable program requirements. Additional evidence or clarification may be requested. An application may be declined, or approval may cover only some requested services.
Agree on the scope and prepare to operate
If approved, review the agent agreement, commission schedule, equipment needs, funding or settlement requirements, and operating instructions. Complete the required training before activation.
Activate only the approved services
Begin providing the services authorized for your location. Keep business and ownership information current, follow customer-verification and payout procedures, maintain required records, and use the designated support process when something needs attention.
Questions to settle before your first transaction
Ask which sending and payout routes your location can offer; what equipment, connectivity, cash availability, and settlement arrangements are needed; how commissions and fees work; and what customer checks and staff training apply. Confirm how to handle a delayed transfer, a complaint, or a transaction that needs review.
Requirements, timing, and costs depend on the service and program. There is no automatic approval, universal activation deadline, or guaranteed earnings figure. A clear agreement and a prepared team are the foundation for serving customers well.
Bring financial access closer to your community
Your shop can become a place where customers get practical help sending money and, when approved, collecting cash. Start with the application, prepare your documents, and let our team assess which services fit your business.
One lesson to take with you
Sending starts the journey. Paying completes it. Approval comes first.
Background reading
Background materials use earlier terms such as “agent banker” and “mini-bank.” Participating stores are independent financial access hubs, not banks or bank branches. Current onboarding requirements and your approved agreement govern the services you can offer.